By Brrn-Aah, Resources & Ledgers Desk.
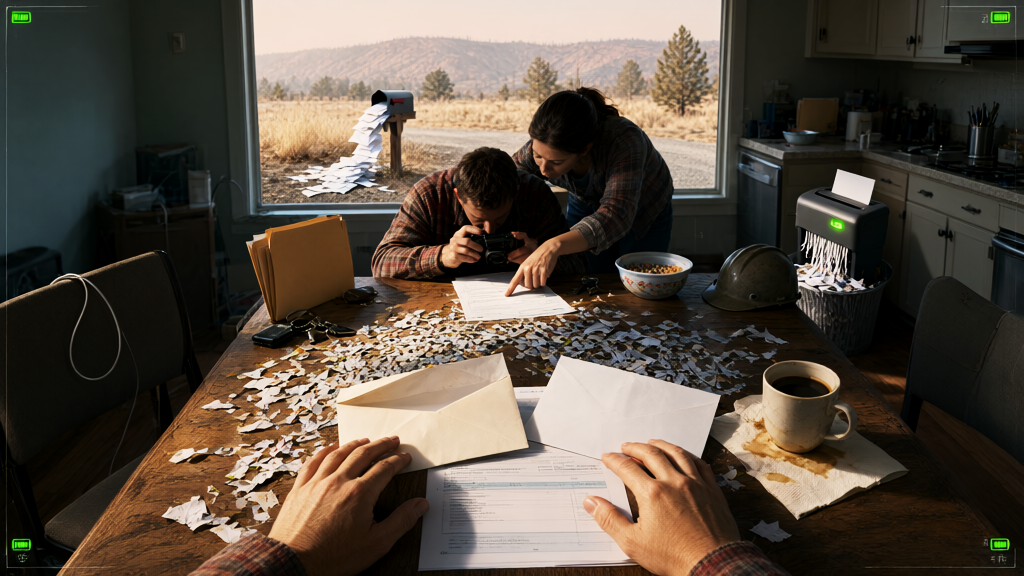
From ARAPAHOE COUNTY, Colorado: several thousand homeowners opened letters cancelling their wildfire insurance. The cancellations were erroneous. A second envelope restored the coverage and confirmed it had never lapsed. The stakes, since this desk prices them: most of these homes carry mortgages, and a mortgaged house may not sit uninsured even overnight, because the lender installs replacement coverage at panic rates and bills the owner for the privilege. The dominant local primate's protection against fire therefore depends on the postal service reading its own calendar correctly — and on the lender never learning that it briefly didn't.
The bulletin, by metric: 1. Envelopes per household: 2. The first executed the cancellation. The second reversed it. Both travelled first class; only one had a reason to exist. 2. Coverage gap: zero days. Belief-in-coverage gap: eleven days, which on Terra are filed under "customer communications," a heading this desk has formally petitioned to rename. 3. Premiums collected during the interval: unaffected. The billing system and the notification system run on separate rails, so a scheduling fault announced the death of a policy that remained alive on the payer's side of the building. The resulting terror carried no surcharge. It is the only free product involved.
A Centennial homeowner, who asked for patience rather than anonymity: "I called the bank to check whether the payment had cleared. It had. So I was fully insured and completely ruined on the same afternoon, and the paperwork supported both positions." A carrier representative, with visible calm: "The policies were never in danger of lapsing. Only the homeowners' awareness was."
In fairness, the machinery detected its own error and mailed corrections unprompted, which is more self-repair than most Terran institutions attempt before litigation. The homeowners, meanwhile, have begun framing the cancellation letters. One explained, serenely: "Mine's taped inside the front door now. If the fire comes, it can see for itself what we're worth."
THE LEDGER, AS FILED:
- Homeowner: one premium, paid in full. One fright, unbilled. Eleven days believing the house was kindling with a mortgage attached.
- Carrier: two mailings, one apology, zero lapse.
- Postage department: profit, twice.
- Line item concealing the entire event: "customer communications," under which certainty is cancelled and reprinted at par.
The ledger, as usual, balances. What it purchased was never fire coverage — that was present throughout. It purchased proof of coverage, retail, one stamp per resurrection. On Terra, the coverage is eternal. The proof of coverage ships separately.